Insurance policies cover you in the event of a “peril”, which is something that causes or can cause a loss. Events that constitute perils can vary from policy to policy, so it’s important to understand the way your provider writes your policy. There are two types of policies that you can purchase: open perils and named perils. An open peril policy covers you for any peril that might cause damage to your dwelling or belongings, while a named perils policy lists specific perils that you are covered for. Let’s take a closer look at open peril vs named peril policies.
What is Open Peril Coverage?
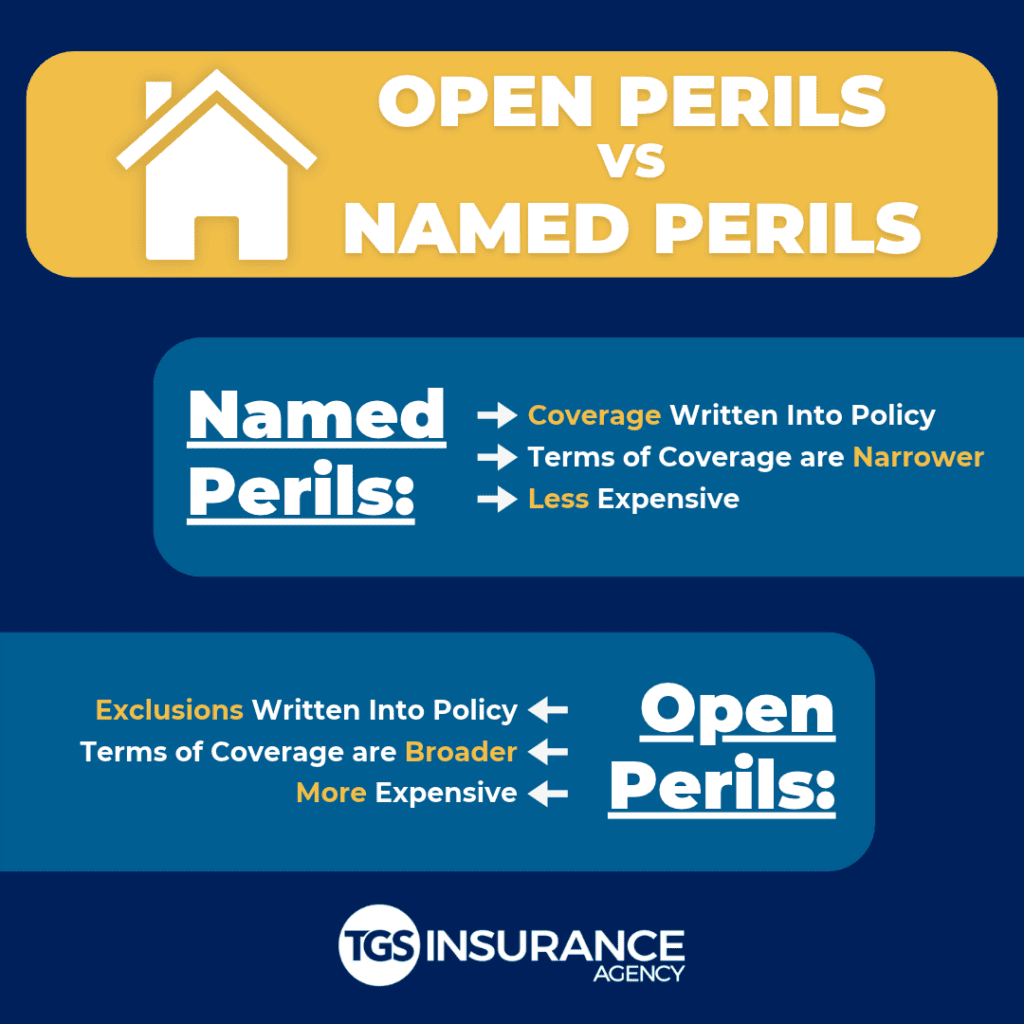
Open peril coverage means that your insurance company will cover you if anything happens to your belongings or home unless it is a named exclusion on your policy. “All perils” is another way to refer to this type of policy. So, unless your policy specifically excludes a peril, your insurance will cover it!
Is Open Perils Coverage Right For Me?
What attracts people to this type of coverage is the full protection of your home and belongings. However, it is more expensive than named peril coverage, but this is simply because of the extensive protection the policy provides. For example, if your home floods and your TV sustains damage, unless your policy specifically lists flooding as an exclusion, your insurance carrier will approve your claim.
TGS Tip: Deciding between open perils and named perils coverage can help you pick which homeowners policy you want! HO-5 and HO-3 mostly differ between which perils they cover.
What is a Named Peril?
Named perils in insurance refers to a list of 16 events that could happen to your personal property or dwelling that could be covered by your insurer. This type of coverage only provides protection for what your provider specifically writes into your policy. If a peril is NOT listed in your policy, then it is NOT covered. You, as the homeowner, will have to pay out-of-pocket. Looking back at the previous example, say your home floods and ruins your TV. If your policy does not list flooding or specifically calls it out as an exclusion, then your insurance will not cover the loss and your claim will be denied.
Is Named Perils Coverage Right For Me?
Named perils coverage typically carries a lower premium than open perils coverage. Additionally, you have the option to purchase additional policies that help fill in the gaps of coverage. For example, if your named perils policy does not cover hail damage, you can add it on to your homeowners policy to ensure you don’t have to pay out-of-pocket in the event that hail causes damage.
What Are The 16 Named Perils in Insurance?
There are 16 perils that every standard homeowners policy typically covers. If any of the following happens to your personal property or dwelling, you will be able to file a claim and receive compensation.
- Fire or lightning
- Theft
- Vandalism
- Windstorms and hail
- Smoke or ash
- Explosions
- Damage caused by vehicles
- Damage caused by aircrafts
- Falling objects
- Freezing of household systems
- Sudden/accidental tearing, cracking, burning or bulging of home systems
- Weight of ice, snow and sleet
- Water overflow or discharge (plumbing, air conditioning and other appliances)
- Power surges
- Riots
- Volcanic Eruptions
Keep in mind that this coverage does extend to belongings outside of your home, as well!
Purchasing an Open Peril vs Named Peril Policy
When you’re deciding between open peril vs. named peril coverage, it’s important to consider a few things:
- Cost of the Policy: It’s a good idea to consider how much you can comfortably spend on a policy. The premium for a named perils policy will be lower. On the other hand, an open perils policy will carry a higher premium due to the broader protection it provides.
- Risk of Claims: If you live in an area that’s at high risk of experiencing perils, such as severe weather events, then it might be a good idea to consider an open perils policy. This ensures that even through the most chaotic of weather, you and your home are covered.
- Peace of Mind: Knowing you and your home are protected no matter what life throws at you makes the cost of an open perils policy worth it for some homeowners. If you’re looking for peace of mind through everything, an open perils policy can help.
There is no wrong answer when it comes to selecting a homeowners policy. If you are comfortable with a named perils policy, then go for it! However, if you’re looking for a policy that keeps you covered in any and all scenarios, open perils is the way to go.
Get The Policy That Works For You With TGS Insurance
Each home is different, and an open perils policy might work best for you, but a named perils policy could be best for your neighbor. It all depends on the amount of coverage you are comfortable with. Thankfully, our trained agents here at TGS Insurance are ready to guide you through the insurance buying process, from initial search to securing discounts, and even making adjustments to your policy later on. Give us a call today to learn more about your policy options and how much you can save on your homeowners insurance!
Open Perils vs Named Perils FAQs
The perils included in your coverage depends on the type of policy you have, either open peril or named perils. If you have an open perils policy, then your policy automatically covers all perils unless it specifically excludes a peril.
No, a peril is not the same as a hazard. A peril is the cause of a loss that leads to a claim. A hazard, on the other hand, is a condition, action or habit that increases the likelihood of a peril happening.
The 16 named perils a named perils policy will cover are fire or lightning, theft, vandalism, windstorms and hail, smoke or ash, explosions, damaged caused by vehicles, damage caused by aircrafts, falling objects, freezing of household systems, sudden/accidental tearing, cracking, burning or bulging of home systems, weight of ice, snow and sleet, water overflow or discharge (plumbing, air conditioning, and other appliances), power surges, riots, and volcanic eruptions.
Which type of policy is better depends on you and your home. You should take into account the cost of each policy, the level of risk your home poses to perils, and how much peace of mind matters to you.