Instant Home Insurance Quote
All We Need Is Your Address, NO BS!
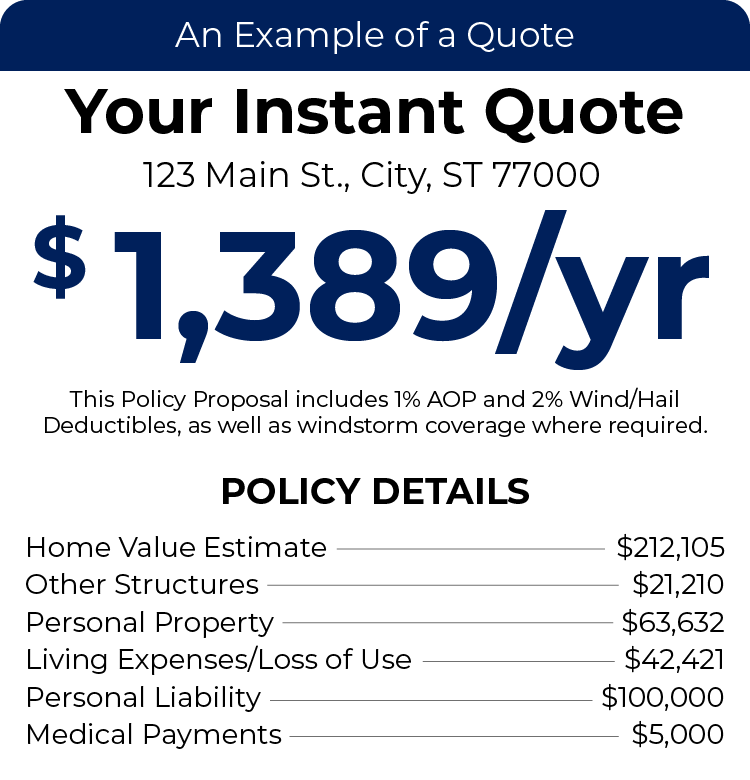
The part of your home insurance policy that helps cover you in the event of a disaster that renders your home unlivable is loss of use coverage. The costs of living in a hotel, or the takeout food you order while your home is under repair can add up quickly. This type of coverage exists to help keep you covered, even if you can’t be home.
What is Loss of Use Coverage on Homeowners Insurance?
Loss of use coverage, also known as additional living expenses (ALE) or Coverage D in your homeowners policy, helps pay for things like hotels, groceries, fuel, and other expenses should your home need to be repaired or rebuilt after a covered loss. For landlords of properties, loss of use coverage can help recoup the lost rent should your tenants need to temporarily live somewhere else.
Another instance in which loss of use coverage would apply is if the local authorities will not let you return home. For example, if your town is hit by a tornado and your house is okay, but the roads and/or area around your home are destroyed and the surrounding area is dangerous, loss of use would help finance a hotel and food for you until your home is ready to return to.
What Does Loss of Use Protection Cover?
Loss of use protection covers costs that accrue as a result of your home being unlivable after damages from a covered peril. Your home insurance policy will help pay for these costs under Coverage D. Expenses usually covered under loss of use coverage include:
- Car rental
- Clothing expenses
- Food expenses
- Fuel or mileage expenses (Ex. your hotel is farther from work)
- Hotel expenses
- Laundry expenses
- Parking fees
- Pet boarding costs
- Public transportation
- Rent for a temporary apartment (if needed)
- Storage until bills
For example, if your home were to catch fire and you are not able to live there while repairs are being done, your insurance company would help with any living costs. If the hotel you’re staying at didn’t have a kitchenette and you had to eat more takeout, insurance would help with that, too.
However, please note that just because your homeowners insurance includes this coverage, it does not mean that you can go on a spending spree and expect insurance to cover it all. Same with all insurance coverages, there are limits. Loss of use only covers what’s deemed “necessary”. And even then, what’s “necessary” will have dollar limits.
Insurance companies will have a list of things that loss of use doesn’t cover so you can be sure you know what your insurance provider will reimburse you for before you spend money.
TGSI Tip: Hold on to every receipt! Your insurance carrier will likely ask for receipts for every purchase to validate any costs incurred. You can also organize everything in a folder or accordion for easy accessibility!
What Does Loss of Use Not Cover?
Loss of use coverage will not cover anything not listed in the covered expenses list your insurance carrier provides you. It also will not cover any bills you were already responsible for. Expenses such as car payments, credit card payments, or other bills are not covered under this coverage.
Home insurance policies are meant to safeguard you against covered perils outside of your control. Anything outside of basic necessities, loss of use coverage will not cover. Additionally, you can’t use loss of use coverage for elective events such as home renovations or general home maintenance.
How Much Loss of Use Coverage Do I Need?
Loss of use coverage is usually based on your dwelling coverage, calculated at about 20% to 30% of your dwelling coverage limit. Consider whether this is enough to cover any necessary increases in your living expenses should you need to be away from home during repairs.
It’s important to remember that there are limits to how much your carrier will reimburse you. Be sure to carry enough loss of use coverage and/or have a padded emergency fund should your living costs exceed your policy limits.
Get The Right Insurance Coverage With TGS Insurance!
Finding the right home insurance policy with the right coverages is always easy with TGS Insurance. Our trained agents shop our bank of over 60 top-rated carriers to find the best deal and coverage for you, taking the hassle of insurance out of your hands. Give one of our agents a call today to learn more about loss of use coverage and how you can save on your homeowners insurance!
FAQs
Loss of use insurance provides financial coverage for housing, food, and necessities should your home undergo a disaster and become inhabitable. It will cover things like hotel and food until your home is ready to return to, within your policy limits.
Loss of use coverage does not have a separate deductible! You will still have your homeowners insurance deductible, but there’s no extra deductible for loss of use claims.
Loss of use usually comes as part of your standard homeowners insurance policy, under Coverage D. Therefore, it does not cost anything extra!
Coverage D on your standard homeowners policy is typically 20%-30% of your dwelling coverage. So, if your dwelling coverage limit is $400,000, a 20% loss of use coverage limit would be $120,000.
Explore Other Homeowners Insurance Coverages:
Recent Homeowners Insurance Articles:
- The Difference Between Home Insurance and Home Warranty
- Understanding Personal Property Coverage Limits
- What is The Difference Between Open Perils and Named Perils?
- Thanksgiving Fire Safety: Avoiding Fire Hazards While Prepping the Big Feast
- Fall Home Maintenance Checklist: Preventing Insurance Claims Before Winter Hits