What Is a Homeowners Insurance Quote?
A quote for your homeowners insurance is the proposed amount that you would pay an insurance carrier to cover your home. This quote is based on various factors, such as your home’s age, building features, location and size, as well as your own insurance score. The proposed amount can change in price as your agent refines the quote so that it’s curated to suit your exact coverage needs. In order to feel confident in your policy before you sign, it’s best to ensure you understand how to read a homeowners insurance quote.
How Do You Get a Homeowners Insurance Quote, and How Long Does it Take?
You can get a free homeowners insurance quote by visiting the carrier’s website or consulting an independent agency like TGS Insurance. The good news is that providing your information to get an insurance quote won’t hurt your credit score! Depending on the carrier or agency, it could take a few days to get your quote. With TGS Insurance, your free home insurance quote is instant! Quotes that are ready quickly are typically based on a small subset of information, and then the initial quote is later refined during the underwriting process. Quotes that take several days are based on more extensive information and are usually the finalized quote.
>> TGSI TIP: Homeowners insurance quotes should always be free. You only pay when purchasing the policy.
What Makes Your Homeowners Insurance Quote High?
Numerous factors are taken into account when calculating your home insurance premium. A high premium is most commonly caused by:
- Attractive nuisances (for example, trampolines)
- High value of personal property
- Low insurance credit score (impacted by claim history)
- Low deductibles
- Building materials and/or size of the house
- Age of the roof and/or house
>> TGSI TIP: Use an independent insurance agency like TGS Insurance to compare quotes for you and find the lowest cost for the coverage you need.
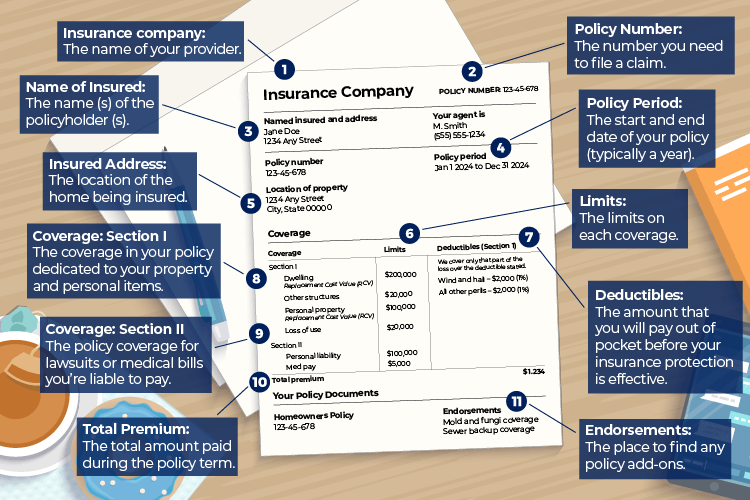
How to Read Your Homeowners Insurance Quote
- 1. Insurance Company
- 2. Policy Number
- 3. Name of Insured
- 4. Policy Period
- 5. Insured Address
- 6. Limits
- 7. Deductibles
- 8. Coverage: Section I
- 9. Coverage: Section II
- 10. Total Premium
- 11. Endorsements
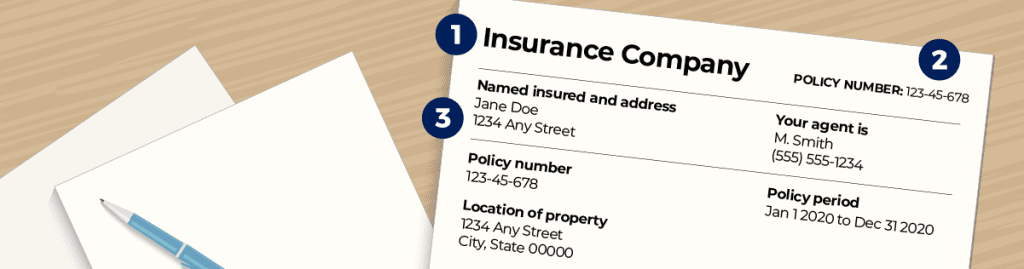
1. Insurance Company
The name of the carrier that will be insuring your home through this policy is listed at the top of your quote. Sometimes, this will be a subsidiary company of a parent insurance carrier. For example, you might receive your insurance through ASI Progressive, part of the Progressive Group of Insurance Companies.
2. Policy Number
The policy number can also be found at the top of your quote. This is the number you will use if you ever need to file a claim. It can be helpful when consulting with your insurance agent, as well. Be sure to keep your policy number somewhere secure.
3. Name of Insured
The quote preparation section of your homeowners insurance quote will list the names on the policy, the billing address, and other general contact information.
4. Policy Period
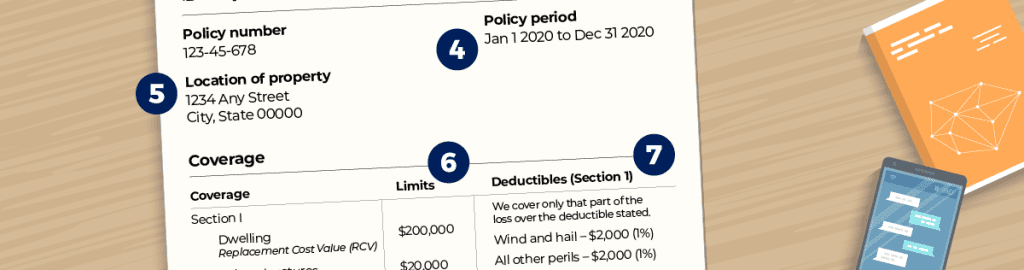
The policy period listed indicates the start and end dates of your insurance coverage with this specific policy. In order to avoid a lapse in home insurance coverage, you will need to renew before the end date listed.
>> RELATED READING: What Is the Difference Between HO2 and HO3 Homeowners Policies?
5. Insured Address
The location of your home is a critical piece of information that determines your homeowners insurance premium. If you only own one home, ensure that your address is correct! If you own multiple properties, double check that the insured location and billing address are both correct.
6. Limits
The limits section of your home insurance quote breaks down the maximum amounts that your policy will pay for each type of coverage. If you suffer damages beyond those limits, you are responsible for paying the rest out of pocket.
7. Deductibles
In the event of a worst-case scenario, your deductible is the money you are obligated to pay out-of-pocket before insurance steps in to foot the rest of the bill. On homeowners policies, you can expect to see an All Perils deductible and/or a Windstorm/Hail deductible, depending on your specific policy. You can always ask your insurance agent to go over which perils, or causes of financial loss, are covered by your policy and fall under the All Perils deductible. If Windstorm/Hail is not included, you may need a separate windstorm insurance policy to secure that coverage.
>> TGSI TIP: If you can afford to raise your deductible, doing so will lower your premium!

8. Coverage: Section I
This section of your home insurance quote explains the coverages relating to your property:
- Coverage A (Dwelling): This covers the structure of your house.
- Coverage B (Other Structures): This covers any other structures on your property that are not directly attached to your house, like your fence or detached garage.
- Coverage C (Personal Property): All of your personal belongings, including your furniture, clothing, and appliances, fall under this coverage when they are on your property. Ask your insurance agent to learn how much coverage your belongings get when they’re off the premises.
- Coverage D (Loss of Use): When your house is uninhabitable following a covered loss, your insurance will provide room and board for a limited time under this coverage. The conditions of this coverage can vary from carrier to carrier, so be sure to clarify this coverage with your agent.
>> TGSI TIP: An insurance quote is a summary of the proposed policy. Your agent will provide your complete policy overview.
9. Coverage: Section II
This section details the coverage you receive when someone is injured or suffers damages to their belongings while on your property. When this happens, you are responsible for paying their financial losses. This is your liability coverage:
- Coverage E (Personal Liability): This covers a claim or lawsuit against you for bodily injury or personal property damage that occurred at your home.
- Coverage F (Medical Payments): Medical payment coverage is the amount your insurance carrier will pay for medical treatment of injuries that happened at your home. This number is typically per person, per accident.
10. Total Premium
The total premium is the sum that you will pay for this homeowners insurance policy. If you choose to pay in either monthly or quarterly installments, the payment breakdown and any other itemized fees that are calculated into the premium will be listed here, too.
>> TGSI TIP: Some carriers offer a discount for paying in full, upfront.
11. Endorsements
This is where you can find any policy add-ons you have opted for. These are optional coverages designed to help round-out the baseline coverage of your standard policy. Reach out to your agent if you’re unsure of which homeowners endorsements are right for your unique insurance and budgetary needs.
>> RELATED READING: Homeowners Endorsements
How to Save Money on Your Homeowners Insurance
Ask Your Agent About Discounts
There are plenty of discounts available to help reduce the cost of your home insurance! Some important discounts are made available once you take measures to make your home more secure. This could mean upping your home security, or earning a windstorm certificate on your coastal home by making it more weather-resistant. These discounts can amount to some massive savings! However, it is always a good idea to shop around for the best deal to ensure you are getting the lowest possible price for the coverage you need.
Coverage & Cost That Work For You
Each carrier calculates quotes differently, so comparing quotes from different carriers can make a huge impact! But finding the time to shop so many different carriers is overall just a big headache. The best way to maximize savings and time is to use an independent insurance agency, like TGS Insurance!
Our mission at TGS Insurance is to find you the best possible deal for the best possible price, without sacrificing the coverage you need. That’s why we shop for your home insurance with our roster of over 60 carriers! Trust our experts to get you a policy that makes sense for you. It starts with a free, instant quote.
A home insurance quote is an estimated proposal of how much you would pay an insurance carrier to cover your home.
You can get a home insurance quote by going to a provider’s website and filling out your information. You can also use an independent agency, like TGS Insurance, to get quotes for you. Calling an agent is another way to get a fast quote.
Your home insurance premium is impacted by many factors, including but not limited to: your location, the age of your house, the age of your roof, building type, and your own insurance score.
A deductible is the amount you would pay in the event of a loss before your insurance kicks in to pay the rest of the bill.
You can ask your insurance agent about the discounts available to you to help offset the cost of your premium.