What Are Homeowners Endorsements?
Homeowners insurance policy endorsements are revisions to a home insurance policy. Sometimes referred to as floaters or riders, these endorsements customize your policy to ensure your coverage is just right for your insurance needs. Sometimes that revision is a reduction in coverage. However, most endorsements will provide extra coverage for gaps existing in a standard home insurance policy. To help you better understand your homeowners endorsement options, we have broken down some of the most popular endorsements available.
Most Common Homeowners Insurance Policy Endorsements
- Personal Property Replacement Cost
- Inland Marine Coverage for High-Value Items
- Equipment Breakdown
- Windstorm and Hail
- Water Damage vs. Water Backup
- Foundation Repair
- Service Line
Personal Property Replacement Cost Endorsement
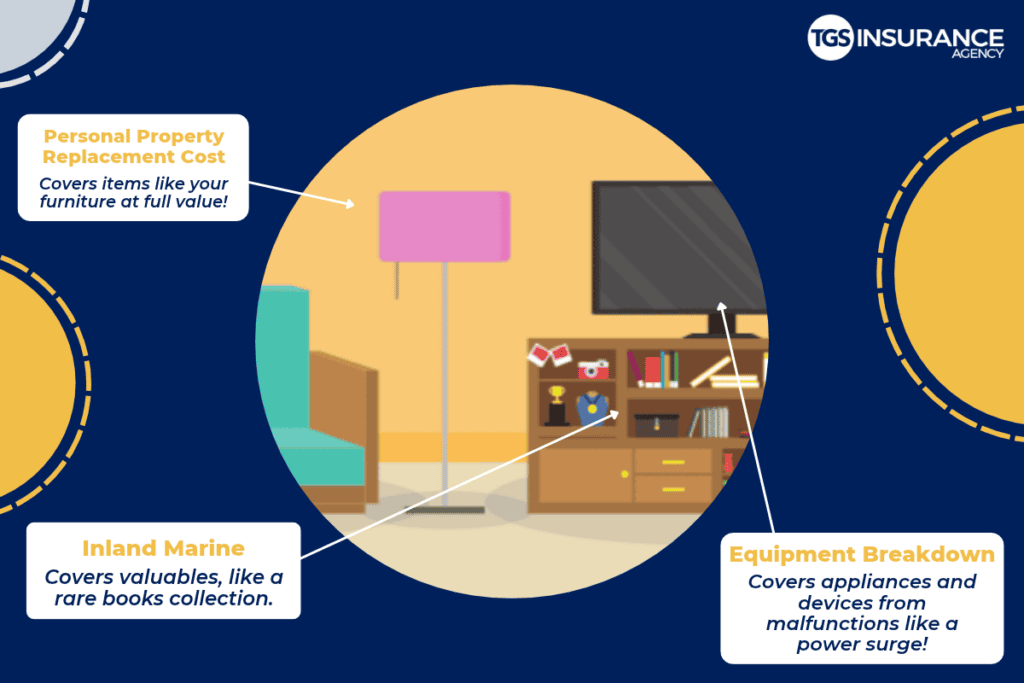
A personal property replacement cost endorsement can add extra coverage for the full replacement cost value, or RCV, of your personal property. When it comes to types of coverage, typically referred to as Coverages A-F, your personal property falls under Coverage C. It’s there to help replace your belongings after disaster strikes. Unfortunately, most policies limit this type of coverage to the actual cash value, or ACV, of the present-day condition of an item. In other words, your insurance won’t give you enough money to replace your belongings in today’s market with ACV coverage. A personal property replacement cost endorsement, however, can add that extra coverage. This endorsement covers the full replacement cost value, or RCV, of your property.
>> RELATED READING: Actual Cash Value vs. Replacement Cost
Inland Marine Endorsement for High-Value Items
A personal inland marine endorsement allows you to insure your most expensive possessions, such as heirloom jewelry, at its full value. This endorsement is also known as scheduled personal property coverage. In addition to limiting personal property coverage to the ACV, most policies set a limit on coverage for your valuables. For example, if your vintage Rolex watch or designer fur collection was stolen, your standard home policy may only cover up to $1,500 for these high-value items. This is where an inland marine endorsement can help! The endorsement bridges the gap between ACV and RCV in your standard policy and covers your high-value personal property for its full value.
It’s important to note that an inland marine endorsement will almost always require an appraisal of the high-value item.
Equipment Breakdown Endorsement
An equipment breakdown endorsement covers the breakdown of your equipment due to internal forces, such as a power surge. When it comes to your appliances or devices you use in your home, like your air conditioner or refrigerator, Coverage C will fund the repair or replacement. But that is only if they’re damaged by an outside force, like a fire. Your policy will not cover the breakdown of your equipment due to internal forces, such as a power surge. An equipment breakdown endorsement comes in to fully cover home appliances or devices.
For more information on factors like the age of your equipment that may impact your deductible, reach out to an insurance agent. They can help you determine if this endorsement is right for you.
>> RELATED READING: Does Home Insurance Cover Appliances?
Windstorm and Hail Endorsement
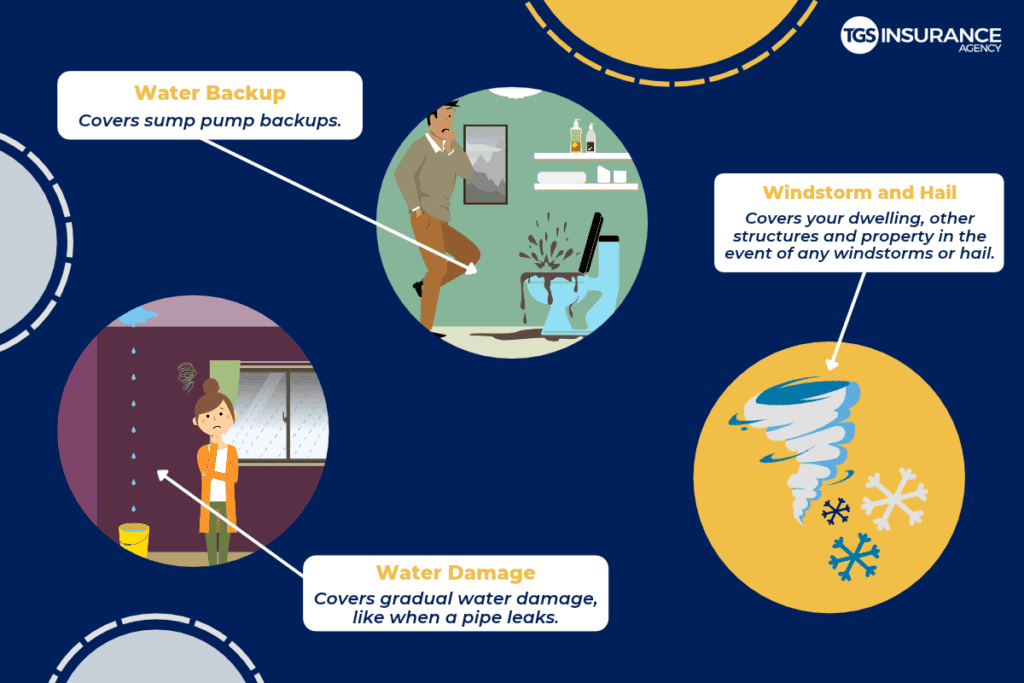
A windstorm and hail endorsement steps in to cover wind or hail damage to your dwelling, other structures, and personal property. Your standalone insurance policy will most likely exclude coverage for these perils. This endorsement helps keep you fully covered in the event wind or hail damage is sustained to your property.
You can also purchase a standalone windstorm coverage policy, depending on the carrier. It may be a good idea to look into wind and hail endorsements or standalone windstorm coverage if you live in an area prone to tornadoes, hurricanes, or hailstorms. Speak with your insurance agent to learn what options are available in your area.
Water Damage Endorsement
A water damage endorsement can cover you for damages caused by slow leakage or seepage of plumbing over time. For example, a leak may cause your ceiling to sag or drip, and you probably wouldn’t even be aware of the leak until it bursts. But your ceiling had been catching the leak for weeks! Standard homeowners policies do not cover this damage. That’s where a water damage endorsement steps in, covering gradual water damage in your home that occurs over time.
>> RELATED READING: Smart Water Leak Detectors: The Impact of IoT on Home Insurance
Water Backup Endorsement
Additionally, a water backup endorsement provides coverage for repairing damages to your home caused by a water backup. Similar to water damage, most homeowners policies don’t provide coverage for these kinds of damages. But water backup can happen to anybody, and having a water backup endorsement in place now can save you immensely in the future. This endorsement can also provide loss of use coverage, which means your insurance carrier will help with the cost of living in a hotel if you are temporarily displaced.
>> RELATED READING: Loss of Use Coverage
Both a water damage endorsement and a water backup endorsement help bridge the gap in coverage for water damages in your home. Your home insurance policy covers only sudden and accidental damage, which usually excludes important perils, or causes, of water damage. That’s where these endorsements help: they make sure you are covered when you need it most.
It’s important to remember that flood insurance will always be a separate policy from your homeowners insurance. Speak with an insurance agent about your coastal tier and how the location of your home impacts your flood insurance rates.
Foundation Repair Endorsement
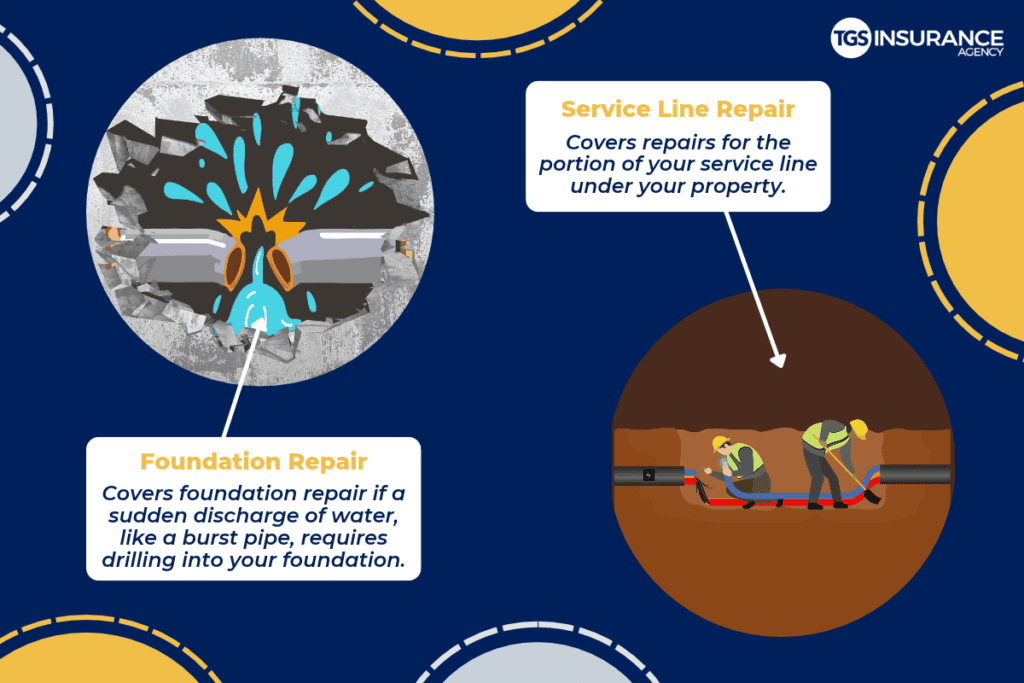
The foundation repair endorsement comes into play to cover any foundation repair related to a sudden and accidental discharge of water. This can be imperative, for instance, if a pipe were to burst under your house. The majority of home insurance policies offer coverage for damages caused by sudden and accidental discharge of water or steam. However, standard policies unfortunately will not fund anything other than the actual pipe repair. This means that you are responsible for covering any costs related to repairing the foundation of your home. This can become an expensive ordeal if your home is built on a slab foundation that needs to be drilled into for pipe access.
A foundation repair endorsement will cover any foundation repair related to a sudden and accidental discharge of water. This very low-cost addition to your standard home insurance policy can save you thousands of dollars in the event of a burst pipe that requires drilling into your foundation.
>> RELATED READING: Does Homeowners Insurance Cover Frozen Pipes?
Service Line Endorsement
A service line endorsement covers the costs of repair when damage is sustained to the service line that runs beneath your yard. Additionally, it will also cover additional costs related to these repairs. This could include necessary excavation, landscaping to replace unearthed trees or plants, sidewalk or driveway repair, and temporary relocation during any period of uninhabitability. This endorsement typically covers up to $10,000, with a small deductible.
This can be incredibly helpful, as your standard homeowners insurance policy will not extend coverage to these repairs. That means without this endorsement, any damages to that portion of your service line are your financial responsibility. A service line endorsement is a much more affordable and extensive option compared to purchasing insurance from each individual company (electric, water, gas, etc.) to cover their specific service line.
Who Needs Homeowners Endorsements?
Homeowners endorsements can be beneficial for all homeowners. Without adding any endorsements to your standard policy, your homeowners insurance will only include basic coverage for your dwelling and property. The most painful time to discover the gaps in your coverage is after a disaster has already struck! Especially if you reside in an area that is prone to natural disasters, if you own any high-value items or appliances that can be costly to repair, or if you don’t have savings set aside for worst-case scenarios. If any of these resonate with you, you could benefit greatly from homeowners endorsements!
Generally, the most common of these endorsements include the ones listed above. But it’s important to note that this is not a complete list of endorsements! There are also endorsements or separate insurance policies available that cover items such as boats or all-terrain vehicles. Extra coverage for liability or personal injury in your home is an option, too! Speaking to an insurance expert can help you better understand which endorsements might be beneficial to you.
>> RELATED READING: 6 Commonly Overlooked Gaps in Home Insurance Coverage That Could Cost You
Find The Right Homeowners Endorsements with TGS Insurance
Our goal here at TGS Insurance is to get you the best coverage for the best price. We shop our roster of over 60 top-rated carriers to find the best rates out there and get you the home insurance you need. Give one of our trained agents a call today to learn how homeowners endorsements can help bridge the coverage gaps in your homeowners insurance policy today!